Best Travel Insurance For Elderly Travelers (2026)

There’s a quiet moment that happens for a lot of travelers somewhere around their seventieth birthday, when a travel insurance quote that used to feel routine suddenly comes back three or four times higher than expected, or worse, the provider they’ve always used simply won’t insure them anymore at all. It’s not personal, and it’s not really about health either, most of the time. It’s just how this particular industry prices and structures risk once age enters the equation, and understanding that structure is genuinely the difference between getting a fair deal and overpaying for less coverage than you actually need.
This guide walks through what actually changes with age in travel insurance, which providers keep the door open the longest, what real costs look like at different ages, and how to shop for this properly rather than accepting the first quote that comes back.
Why Age Changes Everything About This Purchase
Travel insurers price risk, and age is one of the strongest predictors of medical claims they have. That’s the blunt reality behind why a policy that cost eighty dollars at fifty can cost three or four hundred dollars at seventy-five for functionally similar coverage. It’s also why a meaningful number of providers simply stop offering coverage past a certain age entirely, rather than pricing it high and letting the customer decide.
Neither of these facts should be a reason to give up on getting good coverage. They’re reasons to shop specifically among providers built to serve older travelers well, rather than assuming your usual insurer, or the first result in a search, will treat a seventy or 99 year old the same way it treats a 35 year old.
What Age Limits Actually Look Like Across Providers
This is where providers genuinely diverge from each other, and it’s worth knowing the landscape before you start comparing quotes. Some insurers place no age limit at all on their policies. Allianz doesn’t cap age on its plans, and IMG and Seven Corners both extend coverage up to 99 years old across most of their plan lineup, though specific benefits and limits can shift once you’re past eighty.
Other providers draw a firmer line. World Nomads stops offering coverage at seventy, full stop, though its underwriting partner TripAssure runs a separate Silver Nomads program specifically built for travelers past that age. Nationwide similarly limits coverage after seventy on several of its plans. GoReady by Aegis caps its basic plan at 75 but removes that limit entirely on its more comprehensive tiers, an approach a few other insurers mirror, offering a cheaper plan with a hard cutoff and a pricier comprehensive plan with none. Knowing which category a provider falls into before you request a quote saves a genuine amount of wasted time comparing options that were never going to work for your actual age in the first place.
What Actually Costs More As You Age
Real pricing data makes the scale of this jump clear rather than abstract. Comparing fixed benefit plans across several major providers, a 55 year old typically pays somewhere between thirty and two hundred dollars depending on coverage level and plan maximum. That same coverage for a 70 old commonly runs sixty to two hundred ninety dollars, and by eighty, several of those same plans either aren’t available at all or jump to five hundred dollars and beyond for equivalent coverage.
Comprehensive plans follow the same pattern, just at a higher baseline. A fifty year old might pay one hundred twenty five to two hundred sixty dollars for a solid comprehensive plan with medical coverage up to a million dollars, while the identical plan for an eighty year old, where it’s still offered at all, can run seven hundred to over a thousand dollars. This isn’t one insurer being unreasonable, it’s a pattern that holds fairly consistently across the industry, which is exactly why comparing multiple quotes rather than accepting a single provider’s number matters more here than for almost any other type of insurance shopping.
It’s also worth noting that trip length and destination compound this age-related pricing rather than sitting separately from it. A three week trip to a country with expensive private healthcare pushes the premium considerably higher than a one-week trip somewhere with lower average treatment costs, and that gap widens further once age is factored in on top, since insurers are effectively pricing for both a longer exposure window and a higher baseline claims risk at the same time.
What Actually Changes In The Coverage Itself, Not Just The Price
Age doesn’t just affect what you pay, it affects what the policy actually covers, and this deserves just as much attention as the premium. Several plans that offer acute onset pre-existing condition coverage cap that specific benefit at a certain age, commonly seventy nine, after which the acute onset provision simply stops applying even if the base medical coverage continues. Some plans go further and cut off entirely at eighty, offering no coverage at all past that point regardless of price.
This is precisely why reading past the headline coverage number matters so much for older travelers specifically. A plan advertising a million dollars in medical coverage sounds identical whether you’re fifty or eighty, but the actual protections bundled into that number, particularly around pre-existing conditions and evacuation, can differ substantially once age related caps and exclusions are factored in.
Coverage Categories Worth Weighing Beyond Just Medical
Medical coverage understandably gets the most attention, but a genuinely good elderly travel insurance policy covers several other categories worth checking specifically. Trip cancellation and interruption coverage matters more for older travelers in practice, given that health related cancellations, either your own or an accompanying travel companion’s, happen more frequently in this age bracket than for younger travelers. Medical evacuation and repatriation coverage deserves real scrutiny too, since the cost of an emergency flight home scales with both distance and the level of medical support required during transport, both of which trend higher for older travelers with more complex conditions.
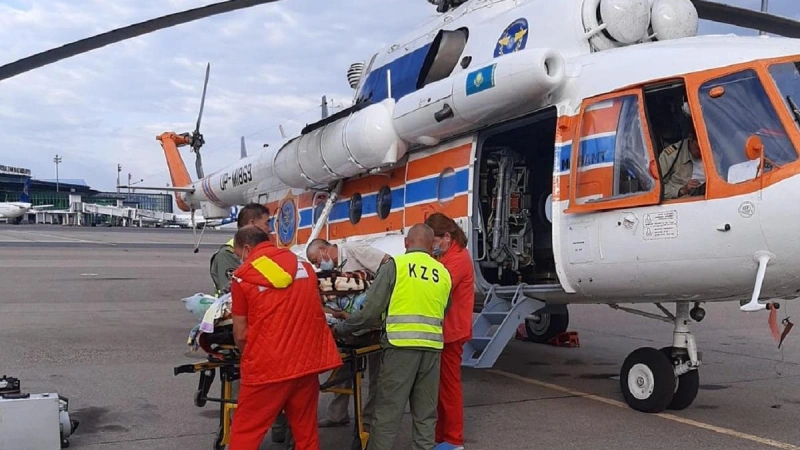
Twenty four hour emergency assistance service quality is worth asking about directly rather than assuming every provider offers the same thing. A genuinely responsive assistance line that can coordinate care, arrange direct billing with local hospitals, and communicate with family back home makes a real difference during an actual emergency, in a way that’s easy to overlook when comparing policies purely on price and coverage limits.
Annual Plans For Travelers Who Go More Than Once A Year
For elderly travelers who take more than one or two international trips annually, a multi-trip annual policy is genuinely worth comparing against buying single trip coverage repeatedly. Options built specifically for this bracket exist at various eligibility ceilings, some annual plans accept applicants up to seventy nine, others extend to eighty five, and a small number of senior specific annual products, often tied to enrollment in Medicare Parts A and B with supplemental coverage, are built exclusively for travelers sixty five and older.
These annual plans typically require maintaining your home country’s primary health coverage alongside the travel policy, and it’s worth confirming that requirement is something you already satisfy before assuming an annual plan is the right fit. For frequent travelers who clear that bar though, the convenience of one annual purchase rather than repeated single trip transactions, combined with often meaningfully lower total annual cost, makes this option genuinely worth the comparison.
Traveling With A Spouse Or Companion Changes The Math Too
A detail worth factoring in specifically for couples traveling together, insurance for two people at different ages, or with different health profiles, doesn’t always price or structure the same way on a joint policy as it would buying two identical individual plans. Some providers price a joint policy based on the older traveler’s age bracket across the board, which can mean paying more for the younger partner’s coverage than necessary. Others allow each traveler’s premium to be calculated individually within a single combined policy, which usually works out better value when there’s a meaningful age gap between travelers.
It’s worth asking a provider directly how they structure pricing for couples or groups rather than assuming, and running the numbers both ways, one joint policy versus two separate individual ones, before committing, since the cheaper option isn’t always the one that looks simpler on the surface.
Reading The Policy Document, Not Just The Quote Summary
The quote you receive up front is a summary, not the actual contract, and it’s worth requesting and actually reading the full policy wording before paying, particularly for anything related to age based exclusions or reduced benefits. A policy summary might list a single medical coverage figure without clearly flagging that acute onset pre-existing coverage drops out at a certain age, or that emergency evacuation benefits reduce past a specific threshold. That kind of detail almost always lives in the full policy document rather than the marketing summary, and the ten minutes it takes to check is considerably cheaper than discovering the gap after a claim.
How To Actually Shop For This Properly
Getting quotes from at least three or four providers before deciding is worth the extra half hour it takes, given how much both price and actual coverage terms vary by provider for this specific age bracket. Comparing acute onset pre-existing condition age limits specifically, not just whether a plan offers the provision at all, catches the kind of gap that only becomes obvious after a claim gets partially denied. If you’re managing an ongoing health condition rather than shopping purely based on age, our guide on travel insurance for seniors with pre-existing conditions goes deeper into exactly that scenario, including the purchase timing window that determines whether a pre-existing condition waiver applies at all.
Checking whether a provider’s age limit applies to the entire policy or just specific benefits, some cut off acute onset coverage at a certain age while leaving base medical coverage intact past that point, avoids assuming a plan is entirely unavailable when actually only one provision within it is affected.
Getting Your Health In Order Before You Shop For Insurance
A pre-trip conversation with your doctor, ideally four to six weeks before departure according to CDC guidance, does double duty here. It confirms you’re fit to travel and flags anything worth discussing with a specialist beforehand, and it also gives you a clear, current picture of your health to reference honestly when filling out an insurance application. The CDC’s official guidance for older travelers covers destination specific vaccine recommendations and other pre-trip health steps worth reviewing alongside, not instead of, sorting out your insurance.
Bringing a copy of your immunization records and a current medication list on the trip itself, beyond just the insurance paperwork, rounds out the kind of preparation that makes both the insurance side and the actual travel considerably smoother if anything does come up while you’re away.
Frequently Asked Questions
Is there travel insurance with no age limit for elderly travelers?
Yes, several major providers, including Allianz, IMG and Seven Corners, offer plans with no upper age limit or coverage extending to ninety nine, though specific benefits like acute onset pre-existing condition coverage may still carry their own separate age caps.
Why does travel insurance get so much more expensive after 70?
Insurers price age as one of the strongest predictors of medical claims, and the jump in cost reflects genuinely higher claims risk in older age brackets rather than an arbitrary markup.
What travel insurance is best for someone over 80?
Providers with no stated age limit, such as IMG, Seven Corners and several comprehensive Visitors Protect style plans, remain among the few realistic options for travelers over eighty, since many mainstream providers stop offering coverage entirely by this age.
Is annual travel insurance worth it for elderly travelers?
Yes, generally, for anyone taking two or more international trips a year. It often works out cheaper overall than repeated single-trip purchases and simplifies the buying process considerably.
Does age affect what a policy actually covers, not just the price?
Yes. Several plans cap acute onset pre-existing condition coverage at a specific age, commonly seventy nine, even while base medical coverage continues past that point, so it’s worth checking specific provisions rather than just the headline coverage limit.
Should I get a doctor’s checkup before buying travel insurance as a senior?
It’s a good idea regardless of insurance, and it also helps you complete an insurance application accurately, since an honest, current picture of your health supports a policy that will actually pay out if you need it.
Final Thoughts
Age doesn’t have to mean settling for worse travel insurance, but it does mean shopping differently than you might have in your fifties. Compare multiple providers rather than defaulting to whichever one insured your last trip, understand where age limits actually sit inside a policy rather than just on its cover page, and weigh annual coverage seriously if you’re traveling more than once a year. Do that, and the extra cost that comes with age buys exactly what it should, real protection for a trip you’ve genuinely earned the right to take, on terms you actually understand going in rather than terms you discover for the first time when it’s already too late to do anything about them.