Best Schengen Visa Travel Insurance in 2026: Complete Guide to Coverage, Cost and Approval

If you are applying for a Schengen visa, there is one document that can make or break your application faster than almost anything else: your Best Schengen Visa Travel Insurance certificate. Every consulate across the 29 Schengen countries checks this paper closely, and a small mistake, like buying a plan with the wrong coverage amount or the wrong validity dates, can lead to a straight rejection.
The good news is that once you understand what consulates actually look for, choosing the right plan takes only a few minutes. This guide walks you through everything: the legal minimum coverage, what a good policy should include, how pricing works, which mistakes cause rejections, and how to pick a plan that protects you properly during your trip, not just on paper.
Whether you are flying out for a holiday in Italy, a business trip to Germany, a family visit in France, or a long backpacking route across several Schengen countries, this article gives you a complete, practical picture so you can buy the right policy the first time.
What Is Schengen Visa Travel Insurance?
Schengen visa travel insurance is a type of travel medical insurance that proves to the consulate you can pay for medical treatment if something goes wrong while you are in Europe. It is not the same as a general trip insurance plan that only covers cancelled flights or lost luggage. The Schengen rules are specific about medical coverage, and a plan that does not meet those exact conditions will be rejected even if it looks like a solid insurance product on paper.
This requirement comes directly from EU regulation. Under Regulation (EC) No 810/2009, every applicant for a uniform Schengen visa must show proof of adequate travel medical insurance that covers repatriation for medical reasons, urgent medical attention, emergency hospital treatment, or death, for the full length of the stay across all member states, with a minimum coverage of 30,000 euros.
Who Actually Needs This Insurance
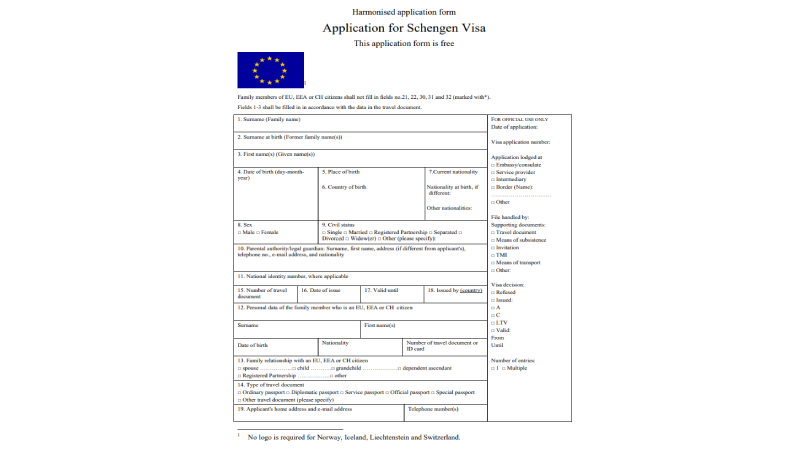
Not every traveller heading to Europe needs to buy this specific type of insurance, so it helps to know where you stand before you shop around.
Travellers who must buy Schengen visa insurance
If you come from a country whose citizens are required to apply for a Schengen visa before entering Europe, for example, India, Nigeria, Pakistan, China, and many others, insurance is compulsory. Your visa application will not even be accepted without a valid certificate attached.
Travellers who are visa exempt
Citizens of countries like the United States, Canada, Australia, Japan, and several others do not currently need a Schengen visa for short stays under 90 days. Insurance is not legally mandatory for them, but it is still strongly recommended, since public healthcare in Europe can be extremely expensive for non-residents without coverage. Starting in 2026, visa-exempt travellers will also need to register through ETIAS before entering the Schengen zone, so it is worth checking the latest rules before you fly.
EU citizens and long-term residents
If you hold an EU passport, you do not need a Schengen visa or travel insurance to move around the zone, since your home country coverage or the European Health Insurance Card already applies.
Minimum Coverage Required by Law
This is the part that trips up most first-time applicants. The consulate does not accept just any travel insurance plan. Your policy must meet all of these conditions at the same time:
- Minimum medical coverage of 30,000 euros (roughly 33,000 to 35,000 US dollars depending on the exchange rate)
- Coverage for emergency hospital treatment and medical care
- Coverage for emergency medical evacuation
- Coverage for repatriation of remains in case of death
- Validity across all Schengen member countries, not just the one you plan to visit first
- Coverage for the entire duration of your stay, including any buffer days
If your policy falls short in even one of these areas, most visa officers will flag it and ask you to correct it, which can delay your application by days or weeks depending on how busy the consulate is.
What a Genuinely Good Plan Should Include
Meeting the legal minimum is one thing, but a good plan does more than just get your visa approved. It actually protects you if something happens during the trip. Look for these features when comparing options.
Zero deductible
A zero deductible means the insurer pays eligible medical costs from the very first euro, with no out-of-pocket amount required from you before the coverage kicks in. Plans with a deductible can leave you paying a few hundred dollars before any claim gets processed, which defeats the purpose during an emergency.
High evacuation and repatriation limits
Basic plans sometimes cap medical evacuation at a low figure, which sounds fine until you actually need an air ambulance from a rural area to a major hospital. Better plans offer evacuation coverage well above a few hundred thousand dollars, since these transports are genuinely costly.
Coverage for pre-existing conditions
If you have a known health condition, check whether the plan covers an acute flare-up of that condition. Many budget plans exclude pre-existing conditions entirely, so read the fine print rather than assuming.
Trip-related add-ons
Some travellers combine the mandatory Schengen medical coverage with add-ons for lost baggage, trip cancellation, flight delay compensation, or personal liability. These are not required by the consulate but add real value if your plan includes them at a reasonable price.
24/7 assistance in your language
A plan with a round-the-clock helpline that can coordinate with local hospitals directly, rather than leaving you to handle paperwork in a foreign language while unwell, is worth paying a little extra for.
How Much Does It Cost?
Pricing depends on a handful of factors, so there is no single fixed price you can quote for every traveller.
Age of the traveller
Older travellers pay more because medical risk increases with age. A 25-year-old and a 65-year-old buying the same coverage amount for the same trip length will see noticeably different premiums.
Length of stay
A 10-day trip costs less to insure than a 90-day trip, since the insurer is on the hook for a longer window of potential claims.
Coverage amount
Plans offering the bare legal minimum of 30,000 euros are usually the cheapest. Plans offering coverage of 50,000 dollars, 100,000 dollars, or higher cost more but offer a bigger safety net.
Deductible level
A zero-deductible plan costs more than one with a 100- or 250-dollar deductible, since the insurer absorbs more of the early cost.
Add-ons selected
Adding trip cancellation, baggage protection, or adventure sports coverage increases the premium but can be worth it depending on your trip.
As a rough guide, many travellers pay somewhere between 15 and 60 dollars for a two-week trip with solid coverage, though this varies widely by provider, age bracket, and the exact benefits chosen. Always compare a few quotes side by side rather than picking the first plan you see, since the price gap between providers for the same coverage can be significant.
Step by Step: How to Buy the Right Plan
Step 1: Confirm your exact travel dates
Insurance must cover your entire trip, including the day you enter and the day you leave. Add a day or two of buffer if your return date is not fully locked in yet, since even a single day gap can lead to rejection.
Step 2: Decide on your coverage amount.
Stick to at least 30,000 euros, but consider going higher if you can afford it, especially for older travellers or longer trips where medical risk is naturally higher.
Step 3: Compare a few providers.
Look at three or four insurers side by side. Check the medical coverage limit, deductible, evacuation limit, and whether pre-existing conditions are covered at all.
Step 4: Read the policy wording, not just the summary page.
Marketing pages often highlight the best features and leave exclusions in smaller print further down. Open the actual policy document before paying.
Step 5: Buy early and download the certificate.
Most insurers issue a PDF certificate immediately after payment. Download it and check that your name, passport number, travel dates, and coverage amount are all correct before submitting it with your visa application.
Step 6: Carry a copy while travelling.
Keep both a digital and printed copy of your insurance certificate with you during the trip. Border officers occasionally ask to see it, and you will need it quickly if you ever have to file a claim.
Common Mistakes That Get Applications Rejected
Buying a domestic health plan and assuming it counts
Many travellers assume their regular health insurance from home will work abroad. Consulates almost never accept domestic plans, since they are not designed to prove coverage across the Schengen zone specifically.
Choosing a coverage amount below 30,000 euros
Some cheaper plans sold as general trip insurance quietly offer less than the legal minimum. Always confirm the exact euro figure stated on the certificate.
Insurance dates that do not match the visa application dates
If your insurance starts a day after your visa dates begin or ends before your planned return, this mismatch is one of the most common and avoidable rejection reasons.
Ignoring the geographical scope
A plan valid only in the country you first land in, rather than the entire Schengen area, does not meet the requirement, since your travel plans could take you across borders.
Forgetting repatriation and evacuation clauses
A plan that only covers hospital bills but skips repatriation of remains or emergency evacuation is incomplete under the regulation, even if the medical coverage amount looks sufficient.
READ MORE: Cheapest Schengen Travel Insurance with 30,000 Euro Coverage
Schengen Visa Insurance vs Regular Travel Insurance
People often confuse these two, so it helps to separate them clearly.
Regular travel insurance usually focuses on trip cancellation, delayed flights, lost baggage, and sometimes a smaller medical component. It is built around protecting your money, not proving compliance with a visa rule.
Schengen visa insurance is built specifically to satisfy the EU regulation. Its core purpose is medical coverage of at least 30,000 euros, full geographic validity, and coverage for the entire stay. Some providers sell combined plans that satisfy both purposes, which is usually the smarter choice if you want a single policy that protects your trip and passes the visa check at the same time.
Special Cases Worth Knowing About
Multiple entry visas
If you are applying for a multiple-entry Schengen visa that allows you to travel in and out over a year or more, your insurance only needs to cover the specific trip you are applying for at that time, not the full validity period of the visa itself. You will typically need a fresh certificate for each new trip.
Family and group applications
Some insurers offer family or group plans where children and elderly parents can be added under one policy. This can be more affordable than buying separate individual plans, though check that the coverage amount applies per person and not as a shared total.
Long stay and student visas
Students or long-stay visa applicants sometimes need coverage for periods well beyond 90 days. Not every travel insurance provider supports this, so long-stay applicants may need to look at specialised expat or long-term health insurance instead of a standard short-trip plan.
Senior travellers
Travellers above 65 or 70 often face higher premiums and sometimes need to answer health declaration questions. It is worth shopping around since pricing for seniors can vary a lot between insurers.
How Consulates Verify Your Insurance
Visa officers typically check three things quickly: the coverage amount stated on the certificate, the date range against your travel itinerary, and whether the insurer name is one they recognise as compliant with Schengen rules. Some consulates keep an informal list of accepted providers based on past experience, so if you are unsure, it can help to check your specific consulate’s website or ask your visa agent whether a particular insurer has a history of smooth approvals in that country.
It is also worth noting that consulates are checking the certificate, not calling the insurer to verify it in most routine cases. That said, submitting a fake or altered certificate is a serious offence that can lead to a permanent visa ban, so always buy from a legitimate provider rather than trying to shortcut the process.
Tips to Get More Value From Your Plan
Buy your insurance only after your travel dates are close to final, since changing dates later usually means buying an entirely new certificate. Check if your credit card already offers travel medical coverage as a card benefit. Some premium cards include partial coverage, though it rarely meets the full 30,000 euro Schengen requirement on its own, so you may still need a standalone plan.
If you travel frequently, look into annual multi-trip travel insurance instead of buying a fresh policy every time, since it can work out cheaper over several trips a year. Always keep the claims process contact number saved somewhere accessible, not just in the PDF certificate, in case your phone or documents are affected by whatever emergency you are dealing with.
Final Thoughts
Buying Schengen visa insurance does not need to feel complicated once you know exactly what the consulate is checking for. Stick to the core requirements: at least 30,000 euros in medical coverage, validity across the entire Schengen area, full trip duration coverage, and clear provisions for emergency evacuation and repatriation. Beyond that legal minimum, spend a little extra time comparing zero-deductible options, evacuation limits, and add-ons that genuinely matter for your specific trip.
A good policy is not just a piece of paper for the visa officer. It is the one thing standing between you and a massive medical bill if something goes wrong far from home. Take the fifteen minutes it requires to compare a few plans properly, buy from a reputable provider, and travel with the confidence that you are actually covered, not just approved.
Frequently Asked Questions
Is travel insurance mandatory for a Schengen visa?
Yes, if you are from a country that requires a Schengen visa, insurance is a compulsory part of the application. Without a valid certificate meeting the minimum requirements, your application will not be processed.
What is the minimum coverage amount required?
The legal minimum is 30,000 euros, which covers medical treatment, hospitalisation, emergency evacuation, and repatriation of remains.
Can I use my domestic health insurance instead?
In almost all cases, no. Domestic health plans are not designed to meet the Schengen regulation and are not accepted by consulates.
Do visa-exempt travellers need this insurance too?
It is not legally required for visa-exempt travellers, but it is strongly recommended, since public healthcare costs for non-residents in Europe can be very high without coverage.
How long before my trip should I buy the insurance?
You can buy it as soon as your travel dates are finalised. Since the certificate needs to match your exact visa application dates, it makes sense to buy it shortly before submitting your application rather than months in advance.
What happens if my trip gets extended while I am already in Europe?
You will need to extend or top up your insurance coverage to match the new dates. Travelling with an expired policy leaves you unprotected and can also cause issues if you need to extend your visa or residence permit locally.
Does the insurance cover COVID-19 or other infectious diseases?
Many current plans include coverage for infectious diseases as part of general medical treatment, but this varies by insurer, so check the specific policy wording rather than assuming it is automatically included.
Can I get a refund if my visa gets rejected?
Most insurers offer a refund or cancellation option if your visa application is denied, provided you have not yet travelled and you submit proof of the rejection. Check the specific refund policy before purchasing.