Best Travel Insurance for UK Trip from India – Honest Comparison 2026

Finding the Best Travel Insurance for UK Trip from India can feel confusing with so many options out there. Let me start with a question most people skip right past – do you actually need travel insurance for your UK trip? Short answer: the UK government does not officially require it for a tourist visa. It is not on the checklist. You can technically fly to London without a single rupee of coverage But here is the thing.
A single visit to a UK hospital without insurance can cost you anywhere from GBP 500 to GBP 5,000. That is roughly Rs 50,000 to Rs 5 lakh. For a basic consultation. If you need surgery or an overnight stay, you are looking at bills that could wipe out your savings. The NHS does not cover tourists for free. Not even emergencies in most cases.
So while it is not mandatory, I would say it is stupid to skip it. Especially when decent plans start at Rs 700-800 for a two week trip. That is less than what you will spend on airport food. I went through five of the most popular travel insurance providers in India, compared them side by side, and I am going to tell you exactly which one is the best travel insurance for UK trip from India based on what kind of traveler you are. No fluff, no affiliate nonsense. Just an honest breakdown.
[ez-toc]
Do You Actually Need Travel Insurance for a UK Visa?
Officially? No. The UK Standard Visitor Visa does not list travel insurance as a requirement. Unlike Schengen countries where it is mandatory, the UK leaves it up to you.
But here is what nobody tells you – having travel insurance actually helps your visa application. When the officer sees a travel insurance certificate in your file, it tells them two things. One, you are a prepared traveler who plans. Two, you will not become a burden on the UK healthcare system. Both of those work in your favor, especially if your profile is not the strongest. Beyond the visa, think about what could go wrong on a 7-14-day trip. Lost baggage at Heathrow. A flight delay that makes you miss your connection. Food poisoning that sends you to A&E. A stolen phone in central London. Any one of these can cost you lakhs without insurance. With an Rs 800 policy? Covered.
What Your Travel Insurance Should Actually Cover
Not all plans are built the same. Some give you a fat medical cover but zero help if your flight gets cancelled. Others cover baggage but cap it so low it is useless. Here is what actually matters:
Medical Cover – This Is the Big One
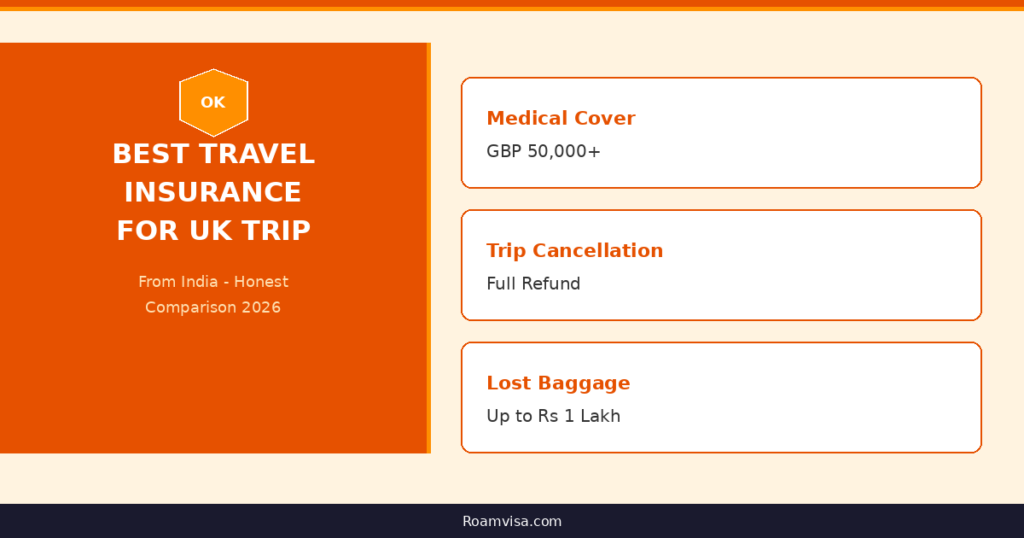
Get a plan with at least GBP 50,000 (roughly Rs 53 lakh) in medical coverage. UK healthcare is expensive for non-residents. An ambulance ride alone can cost GBP 250+. If you need actual treatment, the bills add up fast. Some plans offer GBP 100,000 – even better if you are older or have pre-existing conditions.
Trip Cancellation and Interruption
Flights from India to the UK cost anywhere from Rs 35,000 to Rs 1.5 lakh depending on when you book. If something goes wrong before your trip – family emergency, sudden illness, visa issues – you want that money back. A good plan covers trip cancellation up to the full cost of your prepaid expenses.
Lost and Delayed Baggage
Heathrow handles over 80 million passengers a year. Bags go missing. It happens. Most decent plans cover Rs 50,000 to Rs 1 lakh for lost baggage. For delayed baggage, they give you Rs 5,000-10,000 to buy basics while you wait. Not life changing money, but it helps when your suitcase decides to take a different flight.
Flight Delay Compensation
If your flight gets delayed by more than 6-12 hours, most plans pay out Rs 3,000-5,000 for meals and basic needs. Not a fortune, but when you are stuck at Delhi airport for 10 hours, a free meal is a free meal.
Personal Accident and Liability
This covers accidental death or disability during your trip. Most plans offer Rs 10-25 lakh. Also check for personal liability – if you accidentally damage someone else’s property (it happens more than you think), this covers the legal costs.
What You Can Skip
Adventure sports cover – unless you are actually planning to go bungee jumping in Wales or skiing in Scotland, skip it. It adds to the premium for something you will never use. Same goes for rental car coverage if you are not planning to drive. Keep the plan focused on what you will actually need.
5 Popular Plans Compared Side by Side
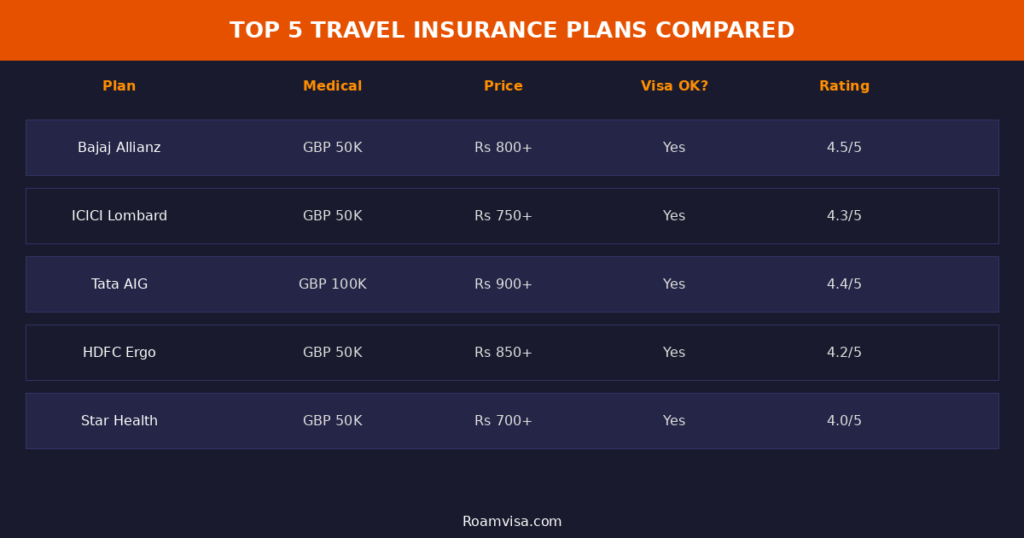
I looked at five providers that Indians commonly use for international travel. These prices are approximate for a 14-day UK trip for one adult aged 25-40. Your actual premium will vary based on age, trip length, and add-ons.
Best Travel Insurance for UK Trip from India
| Provider | Medical | Price (14 days) | Cancellation | Baggage | Rating |
|---|---|---|---|---|---|
| Bajaj Allianz | GBP 50,000 | Rs 800-1,200 | Up to Rs 2L | Rs 60,000 | 4.5 / 5 |
| ICICI Lombard | GBP 50,000 | Rs 750-1,100 | Up to Rs 1.5L | Rs 50,000 | 4.3 / 5 |
| Tata AIG | GBP 100,000 | Rs 900-1,400 | Up to Rs 2L | Rs 75,000 | 4.4 / 5 |
| HDFC Ergo | GBP 50,000 | Rs 850-1,300 | Up to Rs 1.5L | Rs 50,000 | 4.2 / 5 |
| Star Health | GBP 50,000 | Rs 700-1,000 | Up to Rs 1L | Rs 40,000 | 4.0 / 5 |
Quick note: Prices change based on your age, trip length, and which add-ons you pick. These are ballpark figures for a standard 14-day tourist trip. Always check the latest rates on the provider’s website before buying.
My Honest Picks
Best Overall – Bajaj Allianz
If I had to pick just one, it would be Bajaj Allianz. The claim process is straightforward, the cashless hospital network is solid, and the premium is reasonable. Their customer service picks up the phone, which sounds basic but trust me – when you are in a foreign country and need help, that matters more than anything on paper.
Best for Higher Cover – Tata AIG
If you are older than 50, have any health conditions, or just want extra peace of mind, go with Tata AIG. Their GBP 100,000 medical cover is the highest in this list. Yes, the premium is slightly more – maybe Rs 100-200 extra for a 14-day trip. Worth it if you want the safety net.
Cheapest Option – Star Health
Star Health comes in at the lowest price point. If you are young, healthy, and just need basic coverage to tick the box, this works. But the baggage and cancellation limits are lower than the others. You get what you pay for. Fine for a budget trip, but I would not rely on it for anything complicated.
Best for Families – ICICI Lombard
ICICI Lombard offers solid family plans where you can cover everyone under one policy – you, your spouse, and kids. The group discount brings the per-person cost down nicely. Their app is decent too, which helps when you need to file a claim on the go.
How to Buy and Common Mistakes to Avoid
Where to Buy
Buy directly from the insurance company’s website. That is it. Do not buy from random comparison sites that mark up the price. Do not buy from your travel agent who takes a commission and gives you the cheapest plan with the worst coverage. Go to bajajfinserv.in, icicilombard.com, tataaig.com, hdfcergo.com, or starhealth.in and compare yourself. It takes 10 minutes.
When to Buy
Buy it after your visa is approved but before your flight. Some people buy it before the visa appointment to include the certificate in their application. That works too – just make sure the policy dates match your travel dates. Most providers let you cancel for a full refund if your visa gets rejected.
Mistakes People Make
- Buying the cheapest plan without reading what it covers. A Rs 500 plan that covers nothing is worse than no plan at all because it gives you false confidence.
- Not declaring pre-existing conditions. If you have diabetes or BP and do not mention it, the insurer can reject your claim. Be honest. The premium difference is small.
- Wrong travel dates on the policy. If your policy starts on March 15 but your flight lands in London on March 14 because of time zones, you are technically not covered for those first hours. Start your policy one day before departure.
- Not carrying a printed copy. Keep a printout of your policy in your carry-on bag. If something happens at the airport and your phone is dead, that paper could save you.
- Skipping the fine print on exclusions. Most plans do not cover alcohol-related incidents, extreme sports, or self-inflicted injuries. Know what is excluded before you assume you are covered for everything.
How to File a Claim If Something Goes Wrong
Nobody wants to think about this part, but here is the deal. If you need to use your insurance in the UK, follow these steps:
- Call the 24/7 helpline immediately. Every provider has one. Save the number in your phone before you leave India. Most have a WhatsApp option now too.
- For medical emergencies, go to the nearest hospital. If it is cashless, show your policy card. If not, pay out of pocket and keep every single receipt and doctor’s report.
- For lost baggage, file a PIR report at the airport. PIR stands for Property Irregularity Report. Do this before you leave the airport. No PIR, no claim.
- For theft, file an FIR with local police. In the UK, you can report it online through the police website. Get a crime reference number. The insurer will ask for it.
- Submit your claim within 30 days of returning to India. Do not sit on it. Gather all documents – receipts, reports, boarding passes, police reports – and submit through the provider’s app or website.
Special Advice for Senior Travelers
If you are over 60, pay extra attention to this section. Most insurance providers charge higher premiums for senior travelers, and some cap their coverage at age 70 or 75. That does not mean you cannot get coverage – it just means you need to shop smarter.
Tata AIG and Bajaj Allianz both cover travelers up to 80 years old, though the premium will be higher. For a 65-year-old on a 14-day trip, expect to pay Rs 2,500-4,000 instead of Rs 800-1,200. Sounds like a lot, but one hospital visit in the UK will cost ten times that.
READ MORE: Documents You Need for UK Visa from India – Complete Checklist 2026
Declare every health condition – diabetes, blood pressure, heart history, everything. Get a fitness-to-travel certificate from your doctor before the trip. Some insurers ask for it anyway, and it speeds up the claim process if you ever need to use it.
What Travel Insurance Does NOT Cover
Every plan has exclusions, and this is where people get burned. They assume they are covered for everything, something happens, and then they find out their claim is rejected. Here is what almost no plan covers:
- Pre-existing conditions you did not declare. If you knew about it and hid it, the claim is dead.
- Injuries while drunk or on drugs. Self-explanatory. If alcohol was involved, good luck getting that claim approved.
- Adventure sports without the add-on. Skiing, bungee, skydiving – none of these are covered under a standard plan. You need to buy the adventure sports rider separately.
- War zones and civil unrest. Not relevant for the UK, but worth knowing.
- Losses due to your own negligence. Left your bag unattended and it got stolen? That is on you. Insurers expect you to take reasonable care of your belongings.
- Cosmetic or dental treatment. Emergency dental is sometimes covered, but routine dental work or cosmetic procedures – never.
Official Provider Links:
- Bajaj Allianz: bajajallianz.com/travel-insurance
- ICICI Lombard: icicilombard.com/travel-insurance
- Tata AIG: tataaig.com/travel-insurance
- HDFC Ergo: hdfcergo.com/travel-insurance
- Star Health: starhealth.in/travel-insurance
Frequently Asked Questions
Is travel insurance mandatory for a UK tourist visa?
No, it is not. The UK does not require travel insurance for a Standard Visitor Visa. But including it in your application shows the officer you are a responsible traveler. And practically speaking, going without it is a risk not worth taking.
How much does travel insurance for a UK trip cost?
For a 14-day trip, expect to pay between Rs 700 and Rs 1,400 depending on the provider, your age, and the coverage level. Older travelers and those with pre-existing conditions pay more. Family plans bring the per-person cost down.
Can I get a refund if my visa is rejected?
Most providers offer a full refund if you cancel before the policy start date. If your visa gets refused, contact them with your rejection letter and they will process the refund. Check the specific cancellation policy before buying.
Does my plan cover COVID-related issues?
Most plans now include COVID treatment as part of their medical cover. But trip cancellation due to COVID varies by provider. Some cover it, some do not. Read the policy document carefully or call and ask before buying.
Can I buy insurance after reaching the UK?
Technically some providers allow it, but I would not recommend it. Buy before you travel. If something happens during your flight or at the airport, you are already covered. Plus, if you want to include the certificate in your visa application, you need it beforehand.
What if I have a pre-existing health condition?
Declare it when buying the policy. Yes, it might increase your premium slightly. But if you do not declare it and then need treatment for that condition in the UK, your claim will be rejected. Not worth the gamble. Tata AIG has the most flexible coverage for pre-existing conditions in my experience.
Bottom Line
Travel insurance for your UK trip is one of those things that feels like a waste of money until you need it. And when you need it, you will be glad you spent that Rs 800. Pick a plan, make sure it has at least GBP 50,000 medical cover, buy it directly from the provider, and keep a copy on your phone and in your bag. That is it. Do not overthink it. Just get covered and focus on enjoying your trip.